
A ₹6 lakh annual package means the advertised compensation is ₹6,00,000 per year, or ₹50,000 per month when simply divided by 12. However, ₹50,000 is not automatically the amount that reaches your bank account. Your actual monthly take-home depends on whether the ₹6 lakh figure is CTC, gross salary, or fixed cash compensation.
For most salaried employees in India, the main differences come from employer PF contributions included in CTC, employee EPF deductions, professional tax where applicable, insurance or other company deductions, and the way variable pay is structured. Income tax is generally not the biggest deduction at this income level under the current new tax regime, provided the employee qualifies for the applicable rebate.
This guide explains what a ₹6 LPA offer can realistically mean in 2026, how to read the salary breakup, and what you should check before accepting an offer.
What Does 6 LPA Mean?
LPA means lakhs per annum. Therefore:
| Annual package | Simple monthly equivalent |
| ₹6,00,000 per year | ₹50,000 per month |
| ₹6,00,000 ÷ 12 | ₹50,000 |
This ₹50,000 figure is only the annual-to-monthly conversion. It should not automatically be called your in-hand salary.
The most important question is: Does the employer mean ₹6 lakh CTC, ₹6 lakh gross salary, or ₹6 lakh fixed salary?
A ₹6 lakh CTC can produce a lower monthly bank credit than a ₹6 lakh gross salary because CTC may include the employer’s EPF contribution, gratuity, insurance, or variable compensation.
₹6 LPA Salary Structure
There is no single government-mandated breakup for a ₹6 lakh private-sector package. Employers can structure the same annual CTC differently.
A common structure may contain these components:
| Salary component | What it means | Effect on monthly cash |
| Basic salary | Core salary used for several statutory calculations | Included in gross pay |
| HRA | House Rent Allowance, where offered | Usually included in gross pay |
| Other allowances | Employer-defined components | Usually increases gross pay |
| Employee EPF | Employee retirement contribution where applicable | Deducted from salary |
| Employer EPF | Employer contribution | May form part of CTC |
| Gratuity | Employer liability included in some CTC structures | Usually not paid monthly as cash |
| Variable pay | Performance/target-linked component | May not be paid every month |
| Insurance/benefits | Employer-provided benefits | Can form part of CTC |
EPFO documentation states that the standard employee contribution is 12% of applicable EPF wages, while employers also contribute under the EPF framework, subject to the applicable statutory rules and wage basis.
That is why you should never calculate take-home salary by simply dividing CTC by 12.
6 LPA In Hand Salary: How Much Can You Expect?
If ₹6 lakh is your CTC, a realistic take-home amount cannot be stated as one universal figure because the salary structure is unknown.
For example, if an employer includes its statutory contributions and other benefits inside the ₹6 lakh CTC, the amount available as monthly gross cash can be below ₹50,000. Employee PF and other deductions can then reduce the bank credit further.
If the full ₹6 lakh is gross fixed salary, the mathematical monthly gross is ₹50,000 before employee deductions.
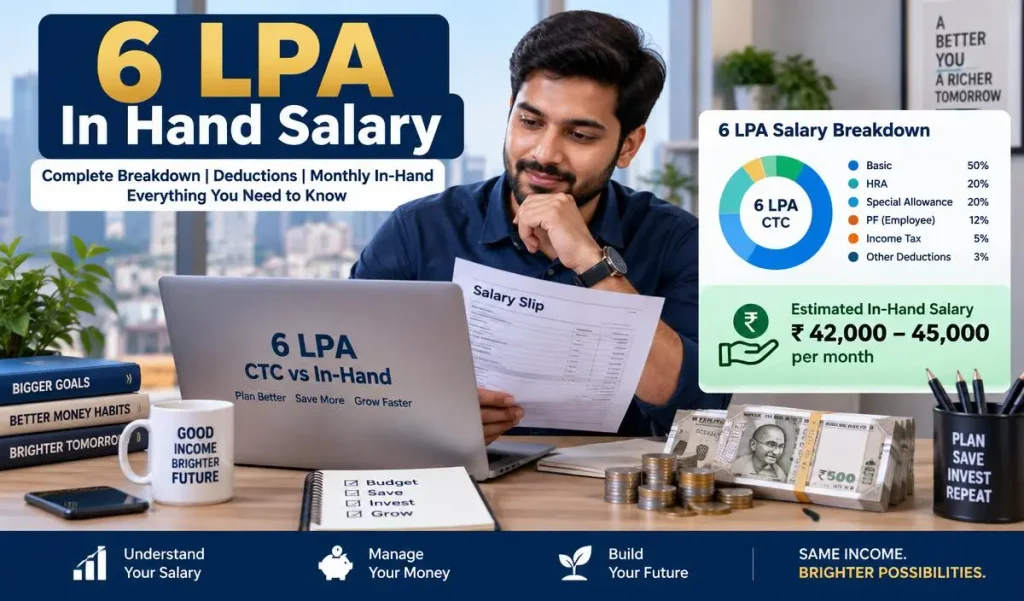
Illustrative take-home scenarios
The following are illustrative calculations, not guaranteed salary offers. The purpose is to show why two employees with the same ₹6 lakh CTC can receive different amounts.
| ₹6 LPA offer type | Monthly amount before deductions | Likely reason for variation |
| ₹6 lakh gross fixed salary | ₹50,000 | Gross divided by 12 |
| ₹6 lakh CTC with employer benefits inside CTC | Below ₹50,000 gross cash is possible | Employer PF, gratuity, insurance or other CTC components |
| ₹6 lakh CTC with variable pay | Fixed monthly amount can be lower | Part of CTC is paid based on performance |
| ₹6 lakh fixed cash compensation | Up to ₹50,000 monthly before employee deductions | Depends on statutory deductions and payroll structure |
So, if someone asks “6 LPA in hand salary per month?”, the safest answer is:
₹50,000 per month is the simple annual equivalent, but actual in-hand pay will normally be lower if ₹6 lakh is CTC or if employee deductions apply.
Income Tax on a ₹6 LPA Salary in 2026
Tax treatment is important, but at this income level the new tax regime can result in little or no income-tax liability for an eligible resident individual.
For AY 2026–27, the Income Tax Department lists the new-regime slabs as:
| Taxable income | New-regime rate |
| Up to ₹4 lakh | Nil |
| ₹4–8 lakh | 5% |
| ₹8–12 lakh | 10% |
| ₹12–16 lakh | 15% |
| ₹16–20 lakh | 20% |
| ₹20–24 lakh | 25% |
| Above ₹24 lakh | 30% |
The department also states that the Section 87A rebate is available up to ₹60,000 where taxable income does not exceed ₹12 lakh, subject to the applicable conditions. Health and education cess is 4% on income tax plus applicable surcharge.
A ₹6 lakh salary is therefore well below the ₹12 lakh taxable-income threshold for the enhanced rebate. However, your exact tax position still depends on the nature of income, regime selected, and applicable rules.
The new tax regime is the default regime for eligible individual taxpayers, although taxpayers can opt for the old regime subject to the applicable conditions.
EPF and Other Take-Home Deductions
EPF is often more important than income tax when estimating monthly cash at this salary level.
Under the standard EPF contribution framework, the employee contribution is 12% of applicable EPF wages. The employer also contributes under the statutory framework.
The important point is that EPF is not necessarily calculated as 12% of your entire ₹50,000 monthly CTC. It depends on the applicable EPF wage basis and the employer’s payroll structure.
Other possible deductions include:
- Professional tax, depending on the state and applicable rules
- Employee EPF contribution
- Employer-provided insurance or benefit deductions, if applicable
- Salary advances or other authorised deductions
- Variable-pay differences
- Tax deducted at source where tax becomes payable
Because these components differ between employers, your offer letter is more useful than a generic online salary calculator.
₹6 LPA Salary by Location
A ₹6 lakh package has the same annual value on paper, but its practical value differs significantly by city.
| Location type | Financial impact |
| Tier-1 cities | Higher rent and commuting costs can reduce disposable income |
| Tier-2 cities | Lower housing costs may leave more disposable income |
| Smaller cities | Living expenses can be lower, although suitable jobs may be fewer |
| Remote role | Potentially lower commuting and relocation expenses |
The salary itself does not automatically receive a nationwide cost-of-living adjustment in private employment. Companies decide compensation based on role, skills, experience, market conditions, location and internal salary bands.
Therefore, ₹6 LPA in Bengaluru or Mumbai can feel very different from ₹6 LPA in a lower-cost city.
₹6 LPA Compared With Other Salary Levels
| Annual package | Simple monthly equivalent |
| ₹3 LPA | ₹25,000 |
| ₹4 LPA | ₹33,333 |
| ₹5 LPA | ₹41,667 |
| ₹6 LPA | ₹50,000 |
| ₹7 LPA | ₹58,333 |
| ₹8 LPA | ₹66,667 |
| ₹10 LPA | ₹83,333 |
These are arithmetic monthly equivalents before PF, tax, variable compensation and other deductions. They should not be interpreted as guaranteed in-hand salaries.
Career Progression From a ₹6 LPA Starting Package
₹6 LPA is a compensation level rather than a career position. Its significance depends heavily on the profession.
For example, ₹6 lakh can represent an early-career package in some technology, finance, operations, sales or professional-service roles. In another field, the same amount could correspond to someone with several years of experience.
A better way to evaluate an offer is to examine:
- Your job title and responsibilities.
- Fixed salary versus variable pay.
- Expected annual increment.
- Promotion criteria.
- Skills you will gain.
- Market salary for the next role.
- Whether the employer provides meaningful training.
- Whether the role improves your future employability.
Do not choose a job solely because its CTC is ₹6 lakh. A slightly lower starting package with strong skill development can sometimes create better long-term career value.
Benefits and Perks
Benefits attached to a ₹6 lakh package vary by employer. Depending on the company, the package may include:
- EPF contributions
- Group health insurance
- Paid annual and sick leave
- Performance bonuses
- Gratuity eligibility where applicable
- Meal, travel or communication allowances
- Learning and certification support
- Hybrid or remote-work arrangements
- Employee wellness benefits
Not every company provides all of these benefits, and some benefits may be counted inside CTC rather than paid as additional cash.
How to Evaluate a ₹6 LPA Job Offer
Before accepting the offer, ask HR for a complete salary breakup.
Check these figures separately:
CTC → fixed gross salary → monthly gross → employee deductions → expected bank credit.
Also ask whether the stated ₹6 lakh includes:
- Annual bonus
- Joining bonus
- Employer PF
- Gratuity
- Insurance premium
- ESOPs or other non-cash benefits
- Performance-linked incentives
A ₹6 lakh package with ₹5.5 lakh fixed compensation can be financially very different from a ₹6 lakh package where a large portion is performance-linked.
Is ₹6 LPA a Good Salary in India?
There is no universal answer.
For a fresher, ₹6 LPA can be a competitive starting package depending on the field and city. For an experienced professional, whether it is attractive depends on years of experience, responsibilities and local market rates.
The biggest advantage is not simply the headline CTC. Look at the fixed component, skill growth, employer quality, promotion prospects and location-adjusted living costs.
Someone earning ₹6 LPA with manageable expenses may have more disposable income than someone earning considerably more in a high-cost city.
FAQs
Is ₹6 LPA equal to ₹50,000 per month?
Mathematically, yes. ₹6,00,000 divided by 12 equals ₹50,000. But ₹50,000 is the monthly equivalent of the annual amount, not necessarily your bank-credit amount.
What is the expected take-home salary from ₹6 LPA?
There is no single exact figure. If ₹6 lakh is CTC, employer PF, gratuity, insurance and variable pay can reduce the monthly cash component. Employee PF and other deductions can reduce it further.
Is there income tax on a ₹6 lakh salary in India?
Under the AY 2026–27 new tax regime, eligible resident individuals with taxable income within ₹12 lakh can qualify for the Section 87A rebate of up to ₹60,000, subject to the applicable conditions.
Does ₹6 LPA include PF?
It can. If an employer quotes ₹6 lakh as CTC, the package may include the employer’s EPF contribution and other benefits. You need to check the company’s salary breakup.
Is ₹6 LPA good for a fresher?
It can be a good starting package, but the answer depends on the profession, city, employer and responsibilities. Fixed salary and future career growth are often more important than CTC alone.
How can I increase my salary after starting at ₹6 LPA?
Build skills that have strong market demand, document measurable achievements, take on higher-responsibility work and benchmark your compensation before switching or negotiating. The best route varies by profession.
Conclusion
A ₹6 lakh annual package works out to ₹50,000 per month before considering the difference between CTC, gross salary and take-home pay. Your actual bank credit depends mainly on the salary structure, EPF and other deductions rather than the headline CTC alone.
Before accepting an offer, ask for the complete breakup and focus on fixed cash compensation, benefits, career growth and your cost of living. That gives you a much more realistic picture of what the offer is worth.